Payactiv

Screenshots
Details
- Rating
- 9.10K reviews
- Version
- 2.2.8
- Developer
- On-demand pay and beyond
Analysis by Norviv
Getting paid on your normal payday can be difficult when an unexpected bill arrives first. I found Payactiv most useful as a finance app built around that exact timing problem: it gives eligible workers a way to access wages they have already earned before the usual pay cycle, while also keeping the wider goal of financial wellness in view. That makes it different from a standard budgeting app or a conventional short-term loan service.
My overall impression is positive, but with an important qualification. The app can be genuinely helpful when the issue is a temporary gap between working and being paid. It is less convincing as a permanent solution to recurring overspending, and it is not something I would treat as a replacement for an emergency fund. The experience also depends heavily on having a reliable connection at the moments when I need to check information or complete an action.
How Payactiv feels in everyday use
Payactiv is a free finance app from On-demand pay and beyond. It is available to an Everyone-rated audience, and its long presence in the category is reflected in its release date of June 4, 2014. The current version is 2.2.8, with a minimum operating system requirement of 10, so device compatibility is worth checking before installing it on an older phone.
The app has built a sizeable audience, with more than a million installs and an average rating of 4.4 from roughly forty-five thousand ratings. Those figures do not guarantee that every worker will have the same experience, because access to earned wages is tied to the user’s employment situation and the way the service is available to that worker. Still, they suggest that Payactiv is not an obscure experiment; it is an established option that many people have tried.
What I like about the concept is that it focuses on money already earned rather than presenting borrowing as the first answer. Imagine working several shifts, then discovering that a utility bill or a necessary car repair is due before payday. A conventional credit card may add interest, and a payday loan can create a much more serious repayment problem. Payactiv is aimed at reducing that timing mismatch.
That distinction matters. I would not describe the app as “free money,” and I would not use early access casually just because it is available. The sensible question is whether bringing earned wages forward solves a specific short-term problem without making the next pay cycle unmanageable. If the answer is yes, the app has a clear purpose. If the answer is no, using it can simply move the pressure rather than remove it.
Where connectivity changes the experience
The most important practical point is that Payactiv is a connected mobile service. When I am checking my available information, trying to understand what can be accessed, or handling an account action, I need a working data connection. A weak signal can turn a quick money check into an uncertain wait, which is especially frustrating when I am standing at a checkout, commuting, or dealing with a bill deadline.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
I would therefore avoid making the app part of a last-second plan. If I know a payment is coming up, I would open Payactiv while I have a dependable connection, review the screen carefully, and allow time for any account information to load. That small habit is more useful than assuming the app will be ready instantly in a basement, parking garage, crowded event, or rural area.
This is also why I would not rely on it as my only emergency resource. A phone with a low battery, a congested network, or an interruption during an important action can make access less convenient at exactly the wrong time. The app may still be valuable, but it should sit alongside ordinary preparation: knowing the bill amount, keeping account details current, and having another payment method available when possible.
Connectivity affects more than speed. It affects confidence. Financial apps need to show current information clearly, and I am uncomfortable making a money decision from a screen that has not fully refreshed. If a page appears incomplete or an action seems stuck, I would stop rather than repeatedly tapping buttons. Checking the connection, reopening the app, and confirming the account state is safer than guessing whether something went through.
Using it on a phone rather than at a desk
Payactiv makes the most sense in mobile situations because the problem it addresses often appears away from a computer. I can imagine using it after a shift, on a break, or while handling an unexpected expense during the day. That convenience is a real advantage over waiting until I reach a desktop to review a financial account.
At the same time, a small screen encourages rushed decisions. I would read each amount and date slowly, particularly if I were tired after work or trying to deal with a stressful bill. The app’s usefulness comes from improving timing, not from making financial choices for me. A few seconds of careful reading can prevent an impulsive transfer or an assumption about what will happen to the next regular paycheck.
One practical workflow I recommend is to separate checking from acting. First, open the app and review the available information. Next, compare it with the bill or purchase that created the urgency. Only then decide whether early access is appropriate. This is a better habit than opening the app at the register and treating the displayed amount as permission to spend it.
Another useful mobile habit is to avoid public Wi-Fi when handling sensitive financial information. If the connection is unreliable, I would wait for a trusted network or use mobile data rather than repeatedly attempting an account action on an unfamiliar hotspot. This is not a reason to avoid the app; it is simply sensible behavior for any service involving wages and personal finances.
People who work irregular hours may find the mobile format particularly convenient. A worker who finishes late may not want to wait for a bank branch or a computer. However, convenience can also encourage frequent checking. I would set a personal rule, such as reviewing the app only when there is a real financial reason, instead of repeatedly checking whether money is available. That keeps the tool focused on planning rather than temptation.
What to do when a connection or action fails
Financial apps deserve a calmer recovery process than social media apps. If Payactiv does not load, my first step would be to confirm whether the phone has a stable connection. I would then close and reopen the app, give the screen time to refresh, and check whether the information has updated before trying anything again.
If an action appears to have failed, I would avoid submitting it repeatedly. Multiple attempts can create confusion about what was accepted, especially when the connection drops after tapping a confirmation control. Instead, I would look for a changed account status or confirmation screen after reconnecting. If the result remains unclear, contacting the appropriate support channel is safer than assuming the money has or has not moved.
This is one area where Payactiv cannot replace good personal records. I would note the bill I am trying to cover and keep track of the amount I intended to access. That makes it easier to spot a mismatch when the app becomes available again. It also prevents a common mistake: treating a temporary loading problem as evidence that more money is available or that an earlier request disappeared.
Recovery is easier when I plan before an emergency. I would install and set up the app while things are calm, rather than waiting until a payment is already overdue. I would also make sure I understand the screens and account information in advance. That preparation reduces the pressure created by a poor signal or an unexpected interruption.
The same principle applies when changing phones or updating an operating system. Since the current version requires at least operating system 10, users with older devices should check compatibility before they depend on the app. A finance tool is most useful when it is available before the crisis, not when installation becomes another problem during it.
Making the app less demanding on data and attention
I would not treat Payactiv as an app that needs to be open constantly. Its purpose is occasional financial action and review, so a data-conscious approach is simple: use it when needed, close it when finished, and avoid repeatedly refreshing screens on a weak connection. This saves attention as much as it saves mobile data.
When I am on a limited data plan, I would prefer a trusted Wi-Fi connection for setup and for any detailed account review, while still remembering that public networks are not ideal for sensitive activity. If I must use mobile data, I would open only the screens relevant to the decision and avoid multitasking with several finance apps at once. The goal is a clear, deliberate session rather than a long browsing habit.
There is also a budgeting benefit to using the app sparingly. Checking earned-wage availability can become psychologically similar to checking a bank balance, but the number should not be confused with disposable income. I would write down fixed expenses first, then consider whether early access fits the remaining plan. This is a non-obvious trade-off: the easier it is to see a possible advance, the more important it becomes to decide based on the whole pay cycle.
For someone trying to improve financial habits, I would pair Payactiv with a basic personal routine outside the app. Keep a short list of upcoming bills, mark which expenses are essential, and decide in advance what kind of situation justifies accessing wages early. That turns the service into a controlled bridge instead of an automatic response to every shortfall.
Users should also think about privacy in ordinary mobile situations. I would avoid opening financial screens where other people can easily see the phone, and I would lock the device when finished. These are small steps, but they matter more when an app is used in workplaces, shared homes, public transport, or busy shops.
Who benefits most, and who should choose another approach
Payactiv is best suited to an eligible worker who has already earned money but faces a temporary mismatch between work and payday. The strongest use case is a necessary expense with a clear amount and a clear reason: an urgent household bill, transport needed to keep working, or another short-term obligation that would otherwise trigger expensive borrowing.
I would be more cautious if the same shortage appears every pay cycle. In that situation, early access may provide relief today while leaving too little for rent, food, or bills later. A budgeting review, a conversation with an employer, or help from a reputable financial counselor may be more useful than repeatedly moving wages forward.
The app is also not the obvious choice for someone who only wants long-term spending analysis. A dedicated budgeting app or a bank’s built-in money-management tools may be better for tracking categories, planning savings, and seeing patterns over several months. Payactiv’s strength is timing earned income, not replacing every kind of financial organization.
Compared with a credit card, the appeal is that the user is working with wages rather than an open-ended credit balance. Compared with a payday loan, the idea is less centered on borrowing against a future repayment obligation. But neither comparison means the decision is costless or automatically wise. I would still examine the terms shown in my own account and consider how accessing money early changes the next regular payment.
Eligibility is another practical question to settle before depending on the service. Because Payactiv is connected to employment and earned wages, not every person will have the same access. I would treat the app as a workplace-linked tool, not as a universal cash app. Someone without a compatible employment arrangement may be better served by a conventional bank account, savings plan, or carefully chosen emergency-credit option.
My verdict on Payactiv’s connected experience
After looking at how the app fits into real mobile situations, I see Payactiv as a focused and potentially useful finance tool rather than a complete financial solution. Its central idea is easy to understand: help workers deal with the gap between earning money and receiving it. That can be meaningful when the alternative is a late bill, an overdraft, or expensive short-term borrowing.
The connected nature of the experience is both a convenience and a limitation. A phone makes access possible during the working day, but a weak network can make an urgent decision harder. I would use it proactively, while connected and calm, rather than waiting until I am offline, rushed, or standing in front of a payment terminal.
My recommendation is strongest for people with a specific, temporary cash-flow problem and a clear plan for the next pay cycle. I would skip it as a routine spending cushion, and I would choose a budgeting-focused alternative if my main goal were tracking expenses or building savings. Used with restraint, Payactiv can be a practical bridge. Used without a plan, it can simply make the same shortage arrive earlier.
For a free finance app with an Everyone age rating and a substantial user base, it is worth considering if its employment-based access fits your situation. Just remember the most important rule I took from the experience: early access should solve a defined timing problem, not become the default way you manage every month.
Frequently Asked Questions
01What is Payactiv, and how does it work?
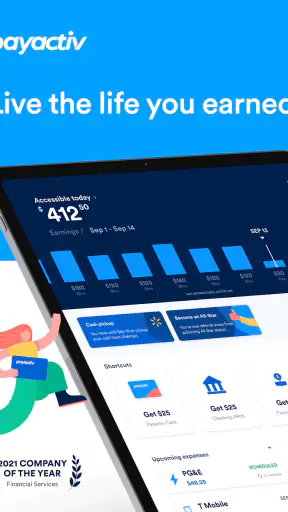
Payactiv is a financial wellness app that can allow eligible employees to access part of their earned wages before the regular payday. After connecting with a participating employer, the app may display wages already earned during the current pay period. Depending on eligibility, users can transfer available funds, use a Payactiv card, or choose other supported payment options.
02Who can use Payactiv?
Payactiv is primarily designed for employees whose employers participate in the Payactiv program. Downloading the app alone does not guarantee access to earned-wage features. Availability depends on your employer, payroll system, location, employment status, and other eligibility requirements. During registration, you may need to verify your identity and provide employment or payroll-related information.
03Are there fees for using Payactiv?
Payactiv’s fees can vary according to the service you select, your employer’s arrangement, and the way you receive funds. Some options may be free, while instant transfers, certain card services, or other features may involve a charge. Before confirming a transaction, review the fee information shown in the app so you understand the total cost.
04How quickly can I receive money through Payactiv?
The delivery time depends on the transfer method and the financial institution receiving the funds. Some supported options may provide access quickly, while standard bank transfers can take longer, particularly outside business hours, on weekends, or during holidays. The app should show the estimated timing before you submit a withdrawal or transfer request.
05Is Payactiv safe to use, and what information does it require?
Payactiv uses account verification and security measures intended to protect personal and financial information, but users should still follow standard safety practices. Registration may require details such as your name, contact information, employment information, identity verification data, and a linked bank account or payment method. Use a strong password, enable available security features, and download the app only from an official store.


